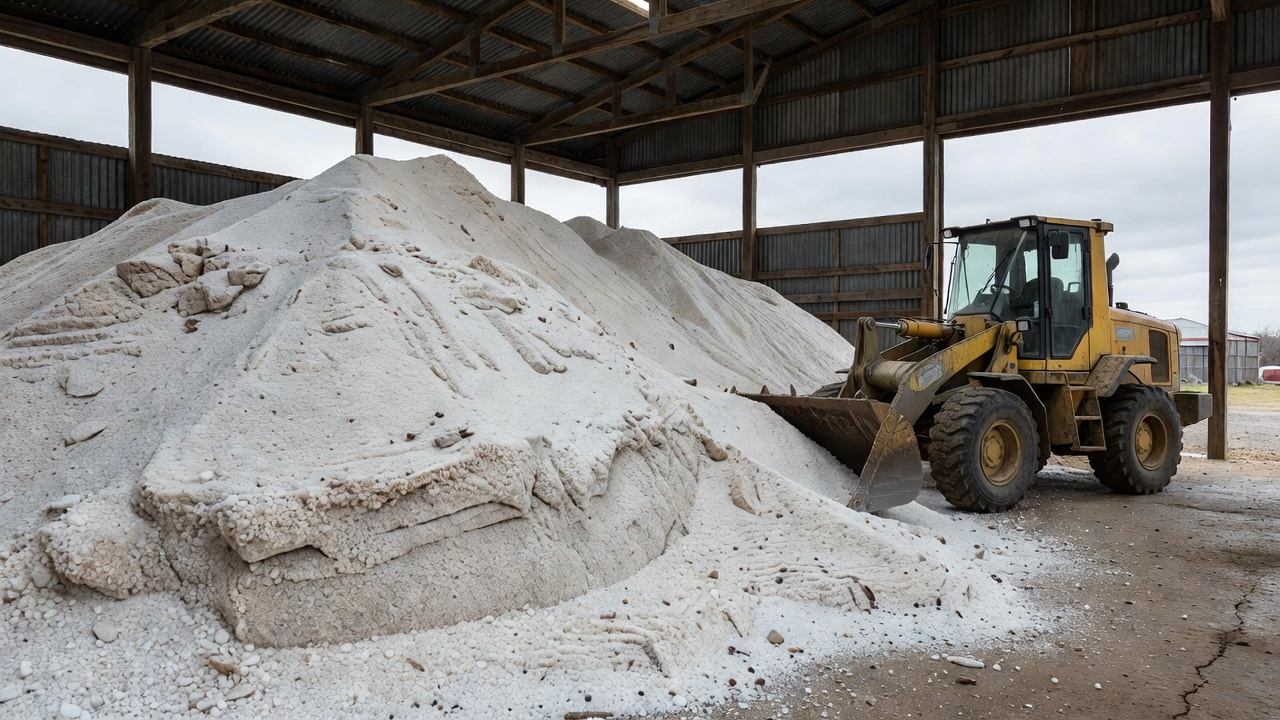
Last winter produced the clearest procurement lesson available to anyone who buys deicer: the commodity did not run out, the logistics did. Detroit-area spot prices reached roughly $300 a ton against contracted tonnage sitting near $100. American Rock Salt declared a shortage and raised commercial customer pricing by $25 a ton. Imported inventory sat at Newark and Baltimore while trucking capacity to move it inland did not materialise in the window when it was needed.
Buyers who had a contract in place paid the contract. Buyers shopping the spot market in January paid triple, when they could get delivery at all. The 2026-27 season is being priced now, and the decision that separates those two outcomes is made in September, not December.
What actually went wrong last season
It is worth being precise about the cause, because the cause tells you which contract terms matter.
North America has not added meaningful underground salt production capacity since American Rock Salt came online in 2001. The continent covers roughly 31% of its salt consumption through imports, which arrive by vessel into a handful of ports and then need inland trucking. That system has no slack. When early heavy snowfall pulled demand forward and Great Lakes–St. Lawrence Seaway shipping windows tightened, the binding constraint became the truck fleet moving bulk salt from port and mine to depot — not tonnage in the ground.
Municipalities were also reported to be receiving priority allocation, which is the normal contractual reality: public road contracts carry firm tonnage commitments and penalties, and suppliers fill those first. Commercial and private-property buyers sat behind them in the queue.
The practical read for a facility manager is that supply risk in this category is allocation risk and delivery risk, not availability risk. Contract language that only fixes price is solving the wrong half of the problem.
The five terms that decided last winter’s outcomes
Firm tonnage with a stated allocation position. A price per ton means nothing if the supplier can fill municipal contracts first and deliver you whatever remains. Ask directly where commercial accounts sit in the allocation order, and get a committed minimum tonnage rather than an estimate. A supplier unwilling to commit tonnage in writing in September is telling you what will happen in January.
A price collar, not a fixed price. Fixed pricing looks attractive after a spike year and is exactly when suppliers are least willing to offer it. A collar — a floor and a ceiling around an index or a base rate — is usually obtainable and caps the outcome that actually hurts. Cap the upside at something you can absorb; the floor is the price of getting the cap.
Delivery-window commitments with a remedy. “Within 48 hours of order” is only meaningful if there is a consequence for missing it. The remedy does not need to be punitive; a credit against the next load, or the right to cover-purchase and bill the difference, changes supplier behaviour more than a liquidated-damages clause nobody will litigate.
Storage terms. The cheapest hedge available is on-site storage, and it is the one most commercial properties do not have. If you have covered storage, pre-season fill at contracted price is the highest-value clause in the agreement. If you do not, ask the supplier about consignment or dedicated reserved tonnage at a third-party depot, and price the covered-storage capital project against three seasons of spot exposure — for many northern properties it pays back inside that window.
Alternative-product substitution rights. Treated salt, magnesium chloride, and calcium chloride blends have different price curves and different supply chains. A contract that lets you substitute at a pre-agreed conversion is a second supply line without a second contract.
Where the price should land
General market bulk rock salt trades in the $30–$80 per ton range in normal conditions, with contracted municipal and commercial tonnage commonly nearer $100 delivered depending on region and haul distance. The $300 spot figure from last winter is the scarcity price, not the market price, and it should not anchor your 2026-27 budget — but the spread between it and contract price is the number that justifies moving early.
A reasonable planning posture for a northern property: budget contracted tonnage at last year’s contract price plus the announced supplier increase, hold a contingency sized at the difference between contract and spot on roughly 20% of your expected usage, and treat that contingency as the cost of not having storage.
Reduce the tonnage, not just the price
The other half of the exposure is application rate, and it is the half you control.
Pre-wetting bulk salt with brine before it leaves the spreader improves adhesion and reduces bounce-and-scatter loss, which in practice cuts material use meaningfully on the same route. Anti-icing — applying brine before the event rather than salt after it — prevents the bond from forming and typically uses a fraction of the material of post-event deicing. Calibrated spreaders and route-specific application rates catch the single largest source of waste, which is a driver running one setting everywhere.
These are not new techniques and most snow contractors can execute them. The reason they often do not is that a per-application contract pays the contractor for material and passes, so the incentive runs the wrong way. If your snow service is contracted per-push with material billed at cost-plus, you are paying your vendor to use more salt. A seasonal fixed-fee or a per-event fee with material included aligns the incentive, at the cost of moving weather risk onto the contractor — who will price it. For most mid-market portfolios the hybrid works best: seasonal fee covering a defined event count, with material included and a stated overage rate.
What to do in the next three weeks
Pull last season’s actual tonnage by property, not the budgeted figure. Ask your current supplier for a firm written quote with committed tonnage for 2026-27, and get a second quote from a supplier whose salt comes from a different source — a domestic mine versus an import terminal, ideally. Confirm where commercial accounts sit in allocation order with both. Then check your snow service agreement for who buys the material and how they are paid for it, because that clause determines whether your careful procurement work gets spent well or spread thin across the lot.
Contractor capacity and supplier tonnage are both allocated before October. Everything available after that is what the early buyers left behind.